Setup
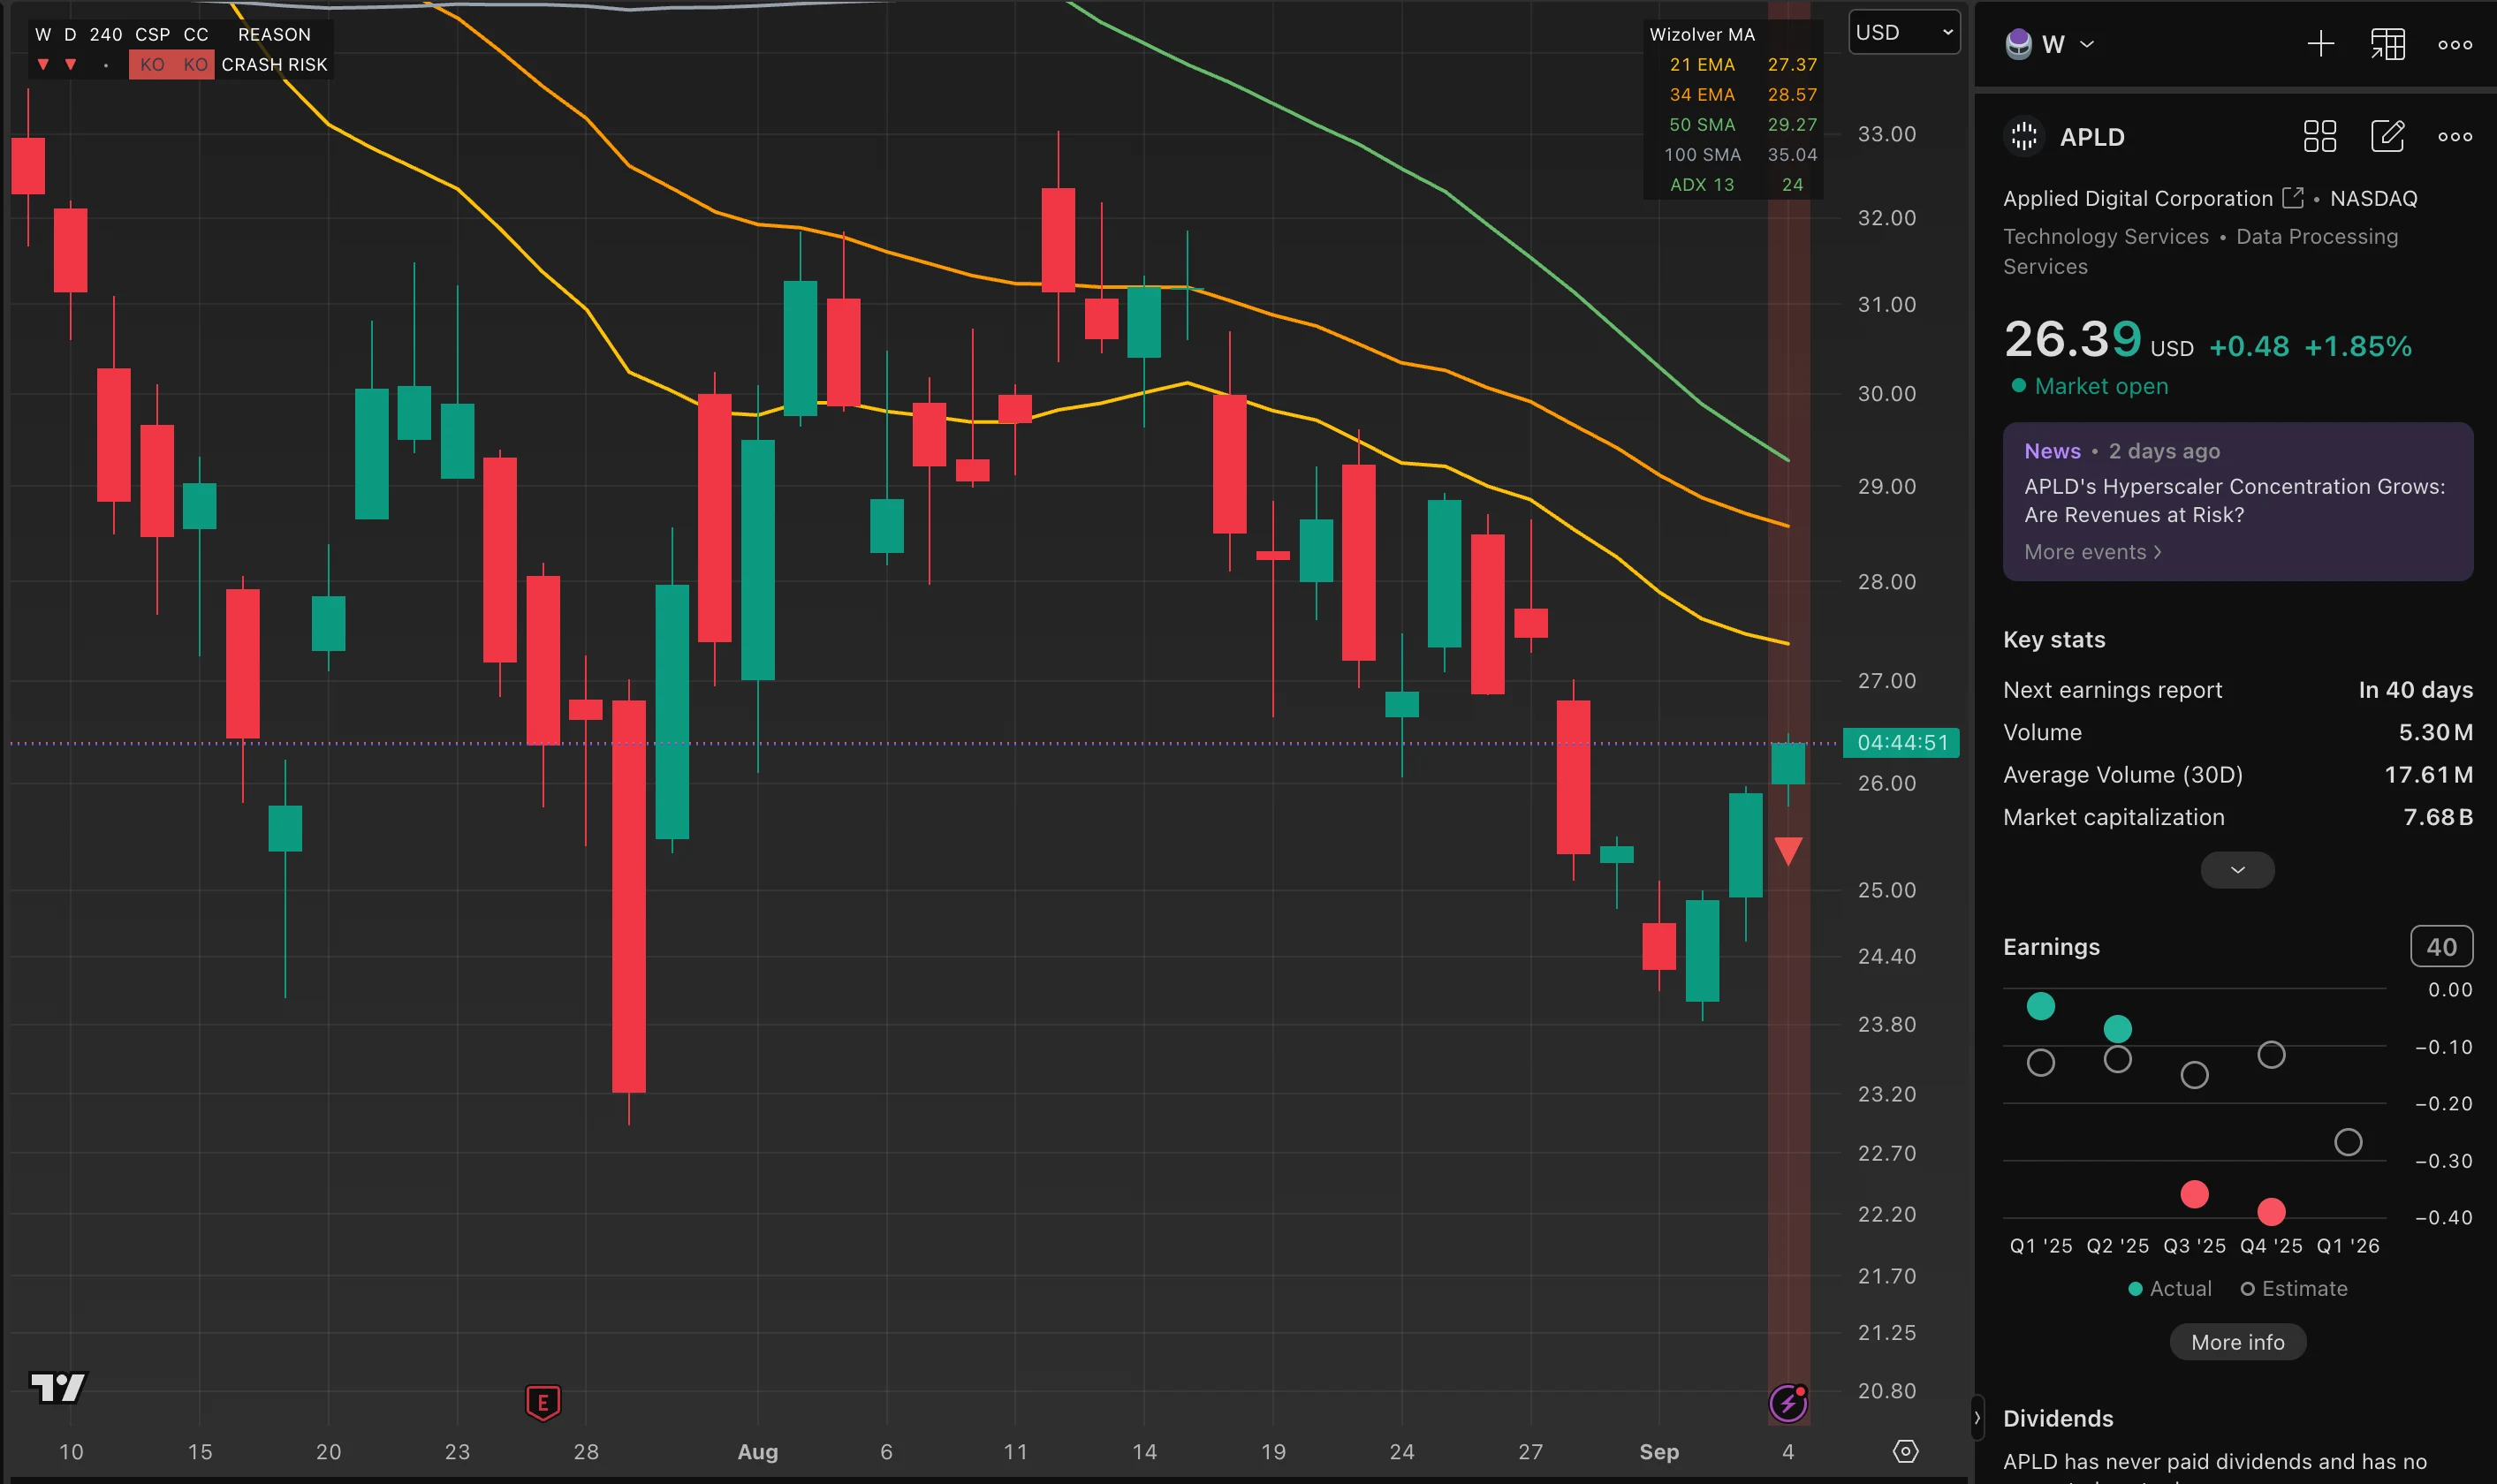
APLD enters a new Cash-Secured Put cycle following a pullback from recent highs. Shares traded around $26.30 at entry after recently falling into the $24 area and beginning to recover.
Price remains below the major moving-average cluster: EMA21 near $27.36, EMA34 near $28.57, SMA50 near $29.27, and SMA100 near $35.04.
The chart does not show a confirmed bullish trend, but location matters. APLD is not extended after a rally; it has pulled back and recently found buyers around $24-$25.
ADX is near 24, stronger than several recent weak-trend CSP setups, but it is not an automatic pass or rejection. The decision is based on the complete assignment structure.
Structure
Cash-Secured Put sold at the $25 strike, expiring September 11 with seven days to expiration.
Premium is $0.42 per share, or $420 across 10 contracts. Cash secured is $25,000.
The premium reduces the effective assignment basis from $25.00 to $24.58. With APLD around $26.30 at entry, the strike sits approximately 4.9% below spot and the effective ownership level approximately 6.5% below spot.
Relevant levels are approximately $26.30 at entry, the $25 strike, the $24.58 effective basis, and the recent $24-$25 support and bounce zone. This is not a deeply OTM CSP; it works because $24.58 is an acceptable ownership price relative to recent structure.
Assignment Logic
This trade is structured around willingness to own APLD.
If APLD remains above $25 through September 11, the puts expire worthless, the $420 premium is retained, and the $25,000 of secured capital is released.
If APLD closes below $25, 1,000 shares enter the portfolio at the $25 strike with an effective ownership basis of $24.58 per share after premium.
That basis sits inside the recent $24-$25 support and bounce area, so assignment is acceptable and would move the position into the Covered Call phase of the Wheel.
The main risk is that the recent $24 area fails and APLD continues materially lower. The effective basis improves entry; it does not create a floor underneath the stock.
Premium Context
Premium is fair.
The September 11 $25 put provides $0.42 per share with seven days until expiration, or $420 across 10 contracts on $25,000 cash secured.
The premium reflects:
- high realized volatility
- recent downside movement
- seven-day expiration
- proximity of the $25 strike
- uncertainty around the $24-$25 support zone
The $420 credit on $25,000 cash secured is a 1.68% return over seven calendar days, or approximately 87.6% simple annualized APR. Implied volatility is approximately 75% while recent historical volatility is around 90%, and IV Rank is relatively low against APLD recent volatility history.
The option is not obviously overpriced and the headline APR is not the thesis. The reason for accepting the trade is that premium lowers potential ownership price to $24.58 inside the recent support structure.
Trade Structure
Management Plan
If APLD remains above $25 through September 11, the puts expire worthless, the full $420 premium is retained, and the $25,000 of secured capital is released.
If assignment occurs, 1,000 shares enter at $25 with an effective basis of $24.58 after premium and transition into Covered Call management.
I am not entering the trade with the objective of avoiding assignment at all costs. The trade exists because $24.58 is currently an acceptable ownership price relative to the recent $24-$25 structure.
If that support breaks materially, any assigned shares will be managed based on conditions after assignment.
The original support area is a reference, not an assumption that it must recover.
Process Note
This trade is not about finding the highest premium available in the chain. The $25 strike already produces a 1.68% return on secured capital in seven days.
Moving closer to the stock would increase premium, but would also increase assignment risk and raise effective ownership price. That trade-off is not needed.
APLD has pulled back from recent highs and reacted around $24. The $25 strike is approximately 4.9% below spot, and the $0.42 credit lowers economic ownership price to $24.58. That is the number that matters.
The annualized return is approximately 88%, but APLD also carries substantial realized volatility: IV is around 75% and historical volatility around 90%. The premium is payment for risk, not free edge. If APLD stays above $25, I collect $420; if assigned, I own 1,000 shares at an effective $24.58. Both outcomes were acceptable before entry.