Setup
HIMS remains under Wheel management with 400 shares assigned at $33. Premium collected during the cycle has reduced effective cost basis to approximately $29.98.
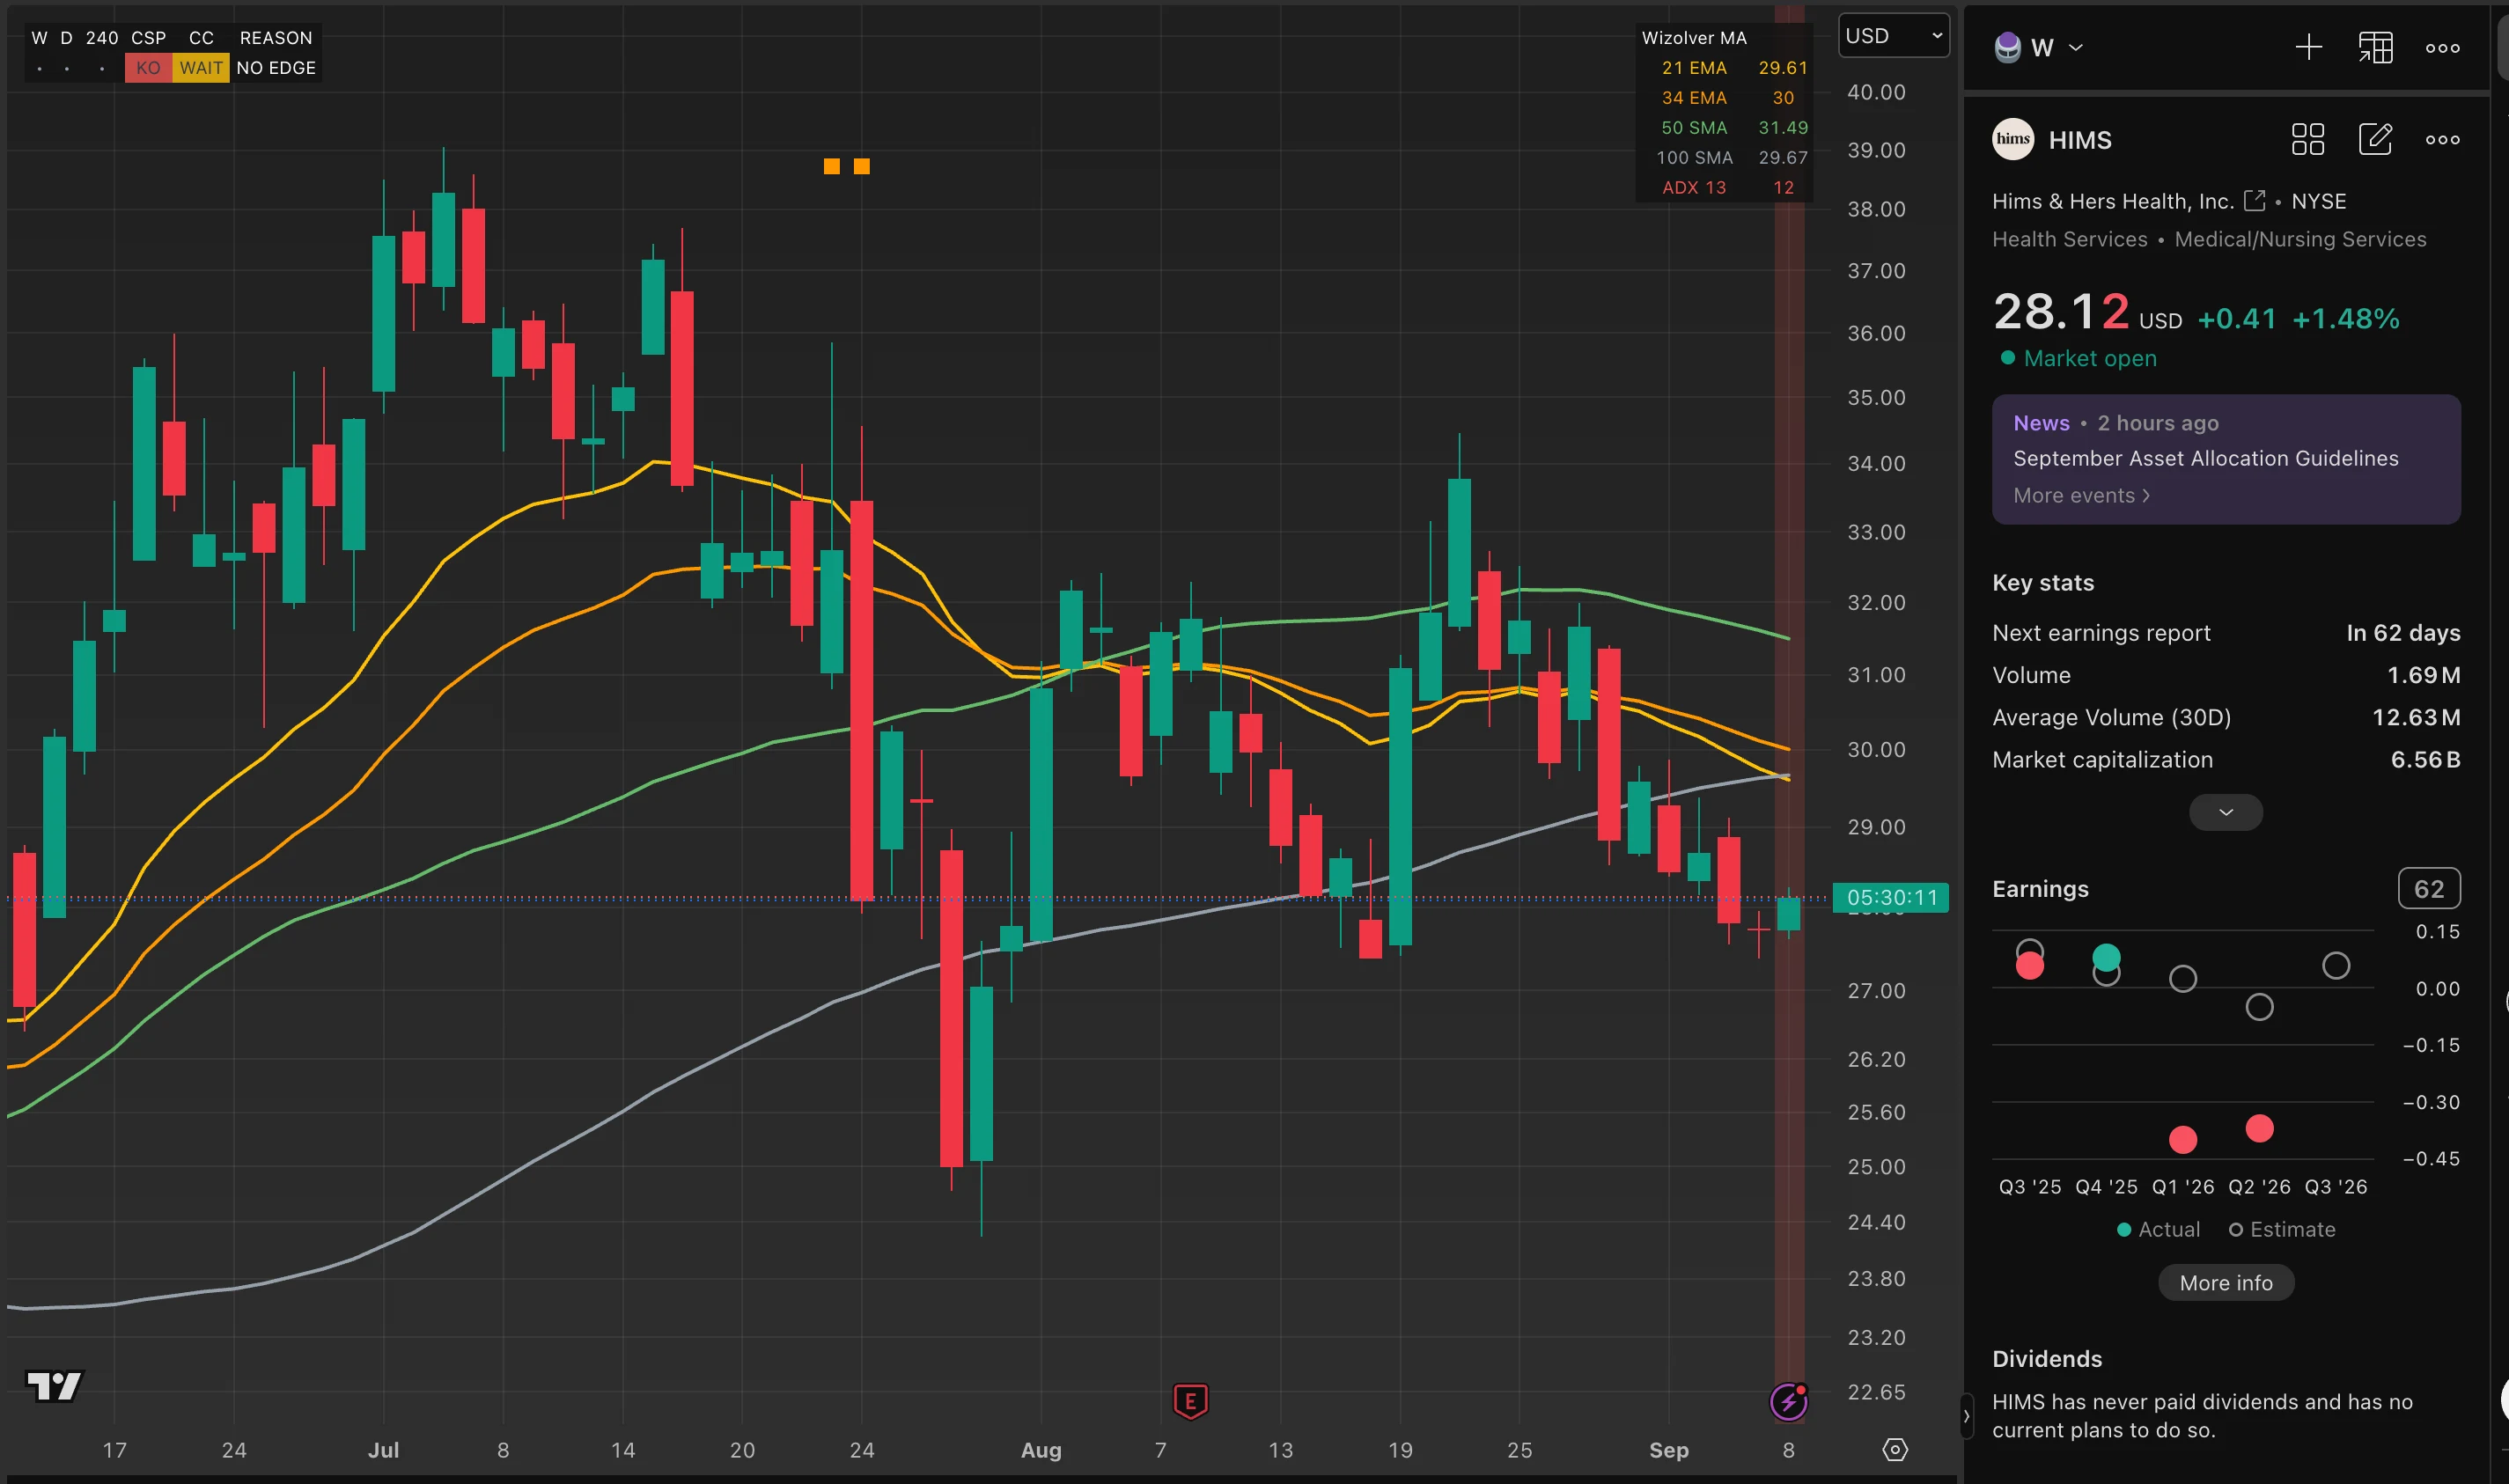
With HIMS around $28, the existing basis remains above market and Covered Call management is less attractive than desired. The chart remains below EMA21, EMA34, SMA50, and SMA100 with low ADX.
The stock is reacting around recent $27.50-$28 support. Rather than buying another 200 shares at market, two $27 Cash-Secured Puts define a lower price where I am willing to increase the position.
This is not a normal standalone CSP. The objective is to improve ownership structure and reduce recovery distance before useful Covered Calls are available again.
Structure
Two Cash-Secured Puts sold at the $27 strike, expiring September 18 with 10 days to expiration.
Premium is $0.80 per share, or $160 across two contracts. Cash secured is $5,400.
The premium reduces effective assignment basis on new shares from $27 to $26.20. The existing 400 shares have an effective basis of approximately $29.98.
If another 200 shares are assigned, blended basis becomes approximately $28.72 across 600 shares, reducing complete-position basis by approximately $1.26 per share. The $26.20 effective ownership price provides room below the $27.50-$28 reaction area; additional exposure is intentionally limited to two contracts.
Assignment Logic
Assignment is an acceptable outcome.
If HIMS remains above $27 through September 18, the puts expire worthless, the $160 premium is retained, and the $5,400 of secured capital is released. Existing 400 shares remain under Wheel management.
If HIMS closes below $27, another 200 shares enter at $27 with an effective basis of $26.20 after premium.
The complete position then consists of 600 shares with an approximate blended effective basis of $28.72, improving recovery profile against the existing $29.98 basis.
The objective is not simply to own more HIMS. It is to bring economic basis closer to market so future Covered Calls can become useful. Additional exposure is deliberate and limited, with no automatic plan to continue adding.
Premium Context
Premium is fair.
The September 18 $27 put provides $0.80 per share with 10 days until expiration, or $160 on $5,400 cash secured.
The premium context is:
- 2.96% return on secured capital
- approximately 108.1% simple annualized APR over 10 days
- implied volatility around 69.5%
- historical volatility near 74.2%
- relatively low IV Rank and no clear volatility edge
The headline APR is high because HIMS carries substantial movement risk. The option is not unusually expensive relative to HIMS own volatility history.
The $160 compensates for accepting another 200 shares at $27. The important figures are the $26.20 effective assignment basis and approximately $28.72 blended basis. Premium is useful; cost-basis improvement is the objective.
Trade Structure
Management Plan
If HIMS remains above $27 through September 18, the puts expire worthless, the $160 premium is retained, and secured capital is released.
I continue managing the existing 400 shares and wait for another recovery opportunity or a price recovery that makes Covered Calls attractive again.
If assignment occurs, another 200 shares enter at $27 with an effective basis of $26.20. The combined position becomes 600 shares with an approximate blended effective basis of $28.72.
Future Covered Calls will be evaluated against the lower blended basis, not sold aggressively simply because it improved.
Two additional contracts are intentional. There is no plan to add automatically if HIMS keeps falling.
Process Note
I already own HIMS. The question was not whether the $27 put looked attractive standalone, but whether assignment would materially improve the existing Wheel position.
Instead of buying another 200 shares around $28, I sold two $27 puts for $0.80. If they expire worthless, I collect $160; if assigned, new shares enter at an effective $26.20 and blended basis falls to approximately $28.72.
The chart remains weak below major moving averages, and the high premium reflects underlying volatility rather than a clear volatility edge. That is why additional exposure is limited to two contracts.
I am not adding because HIMS suddenly became stronger. I am using a defined CSP to improve an existing Wheel position. If HIMS stays above $27, I collect $160; if assigned, I add 200 shares at an effective $26.20. Both outcomes were acceptable before entry.