Setup
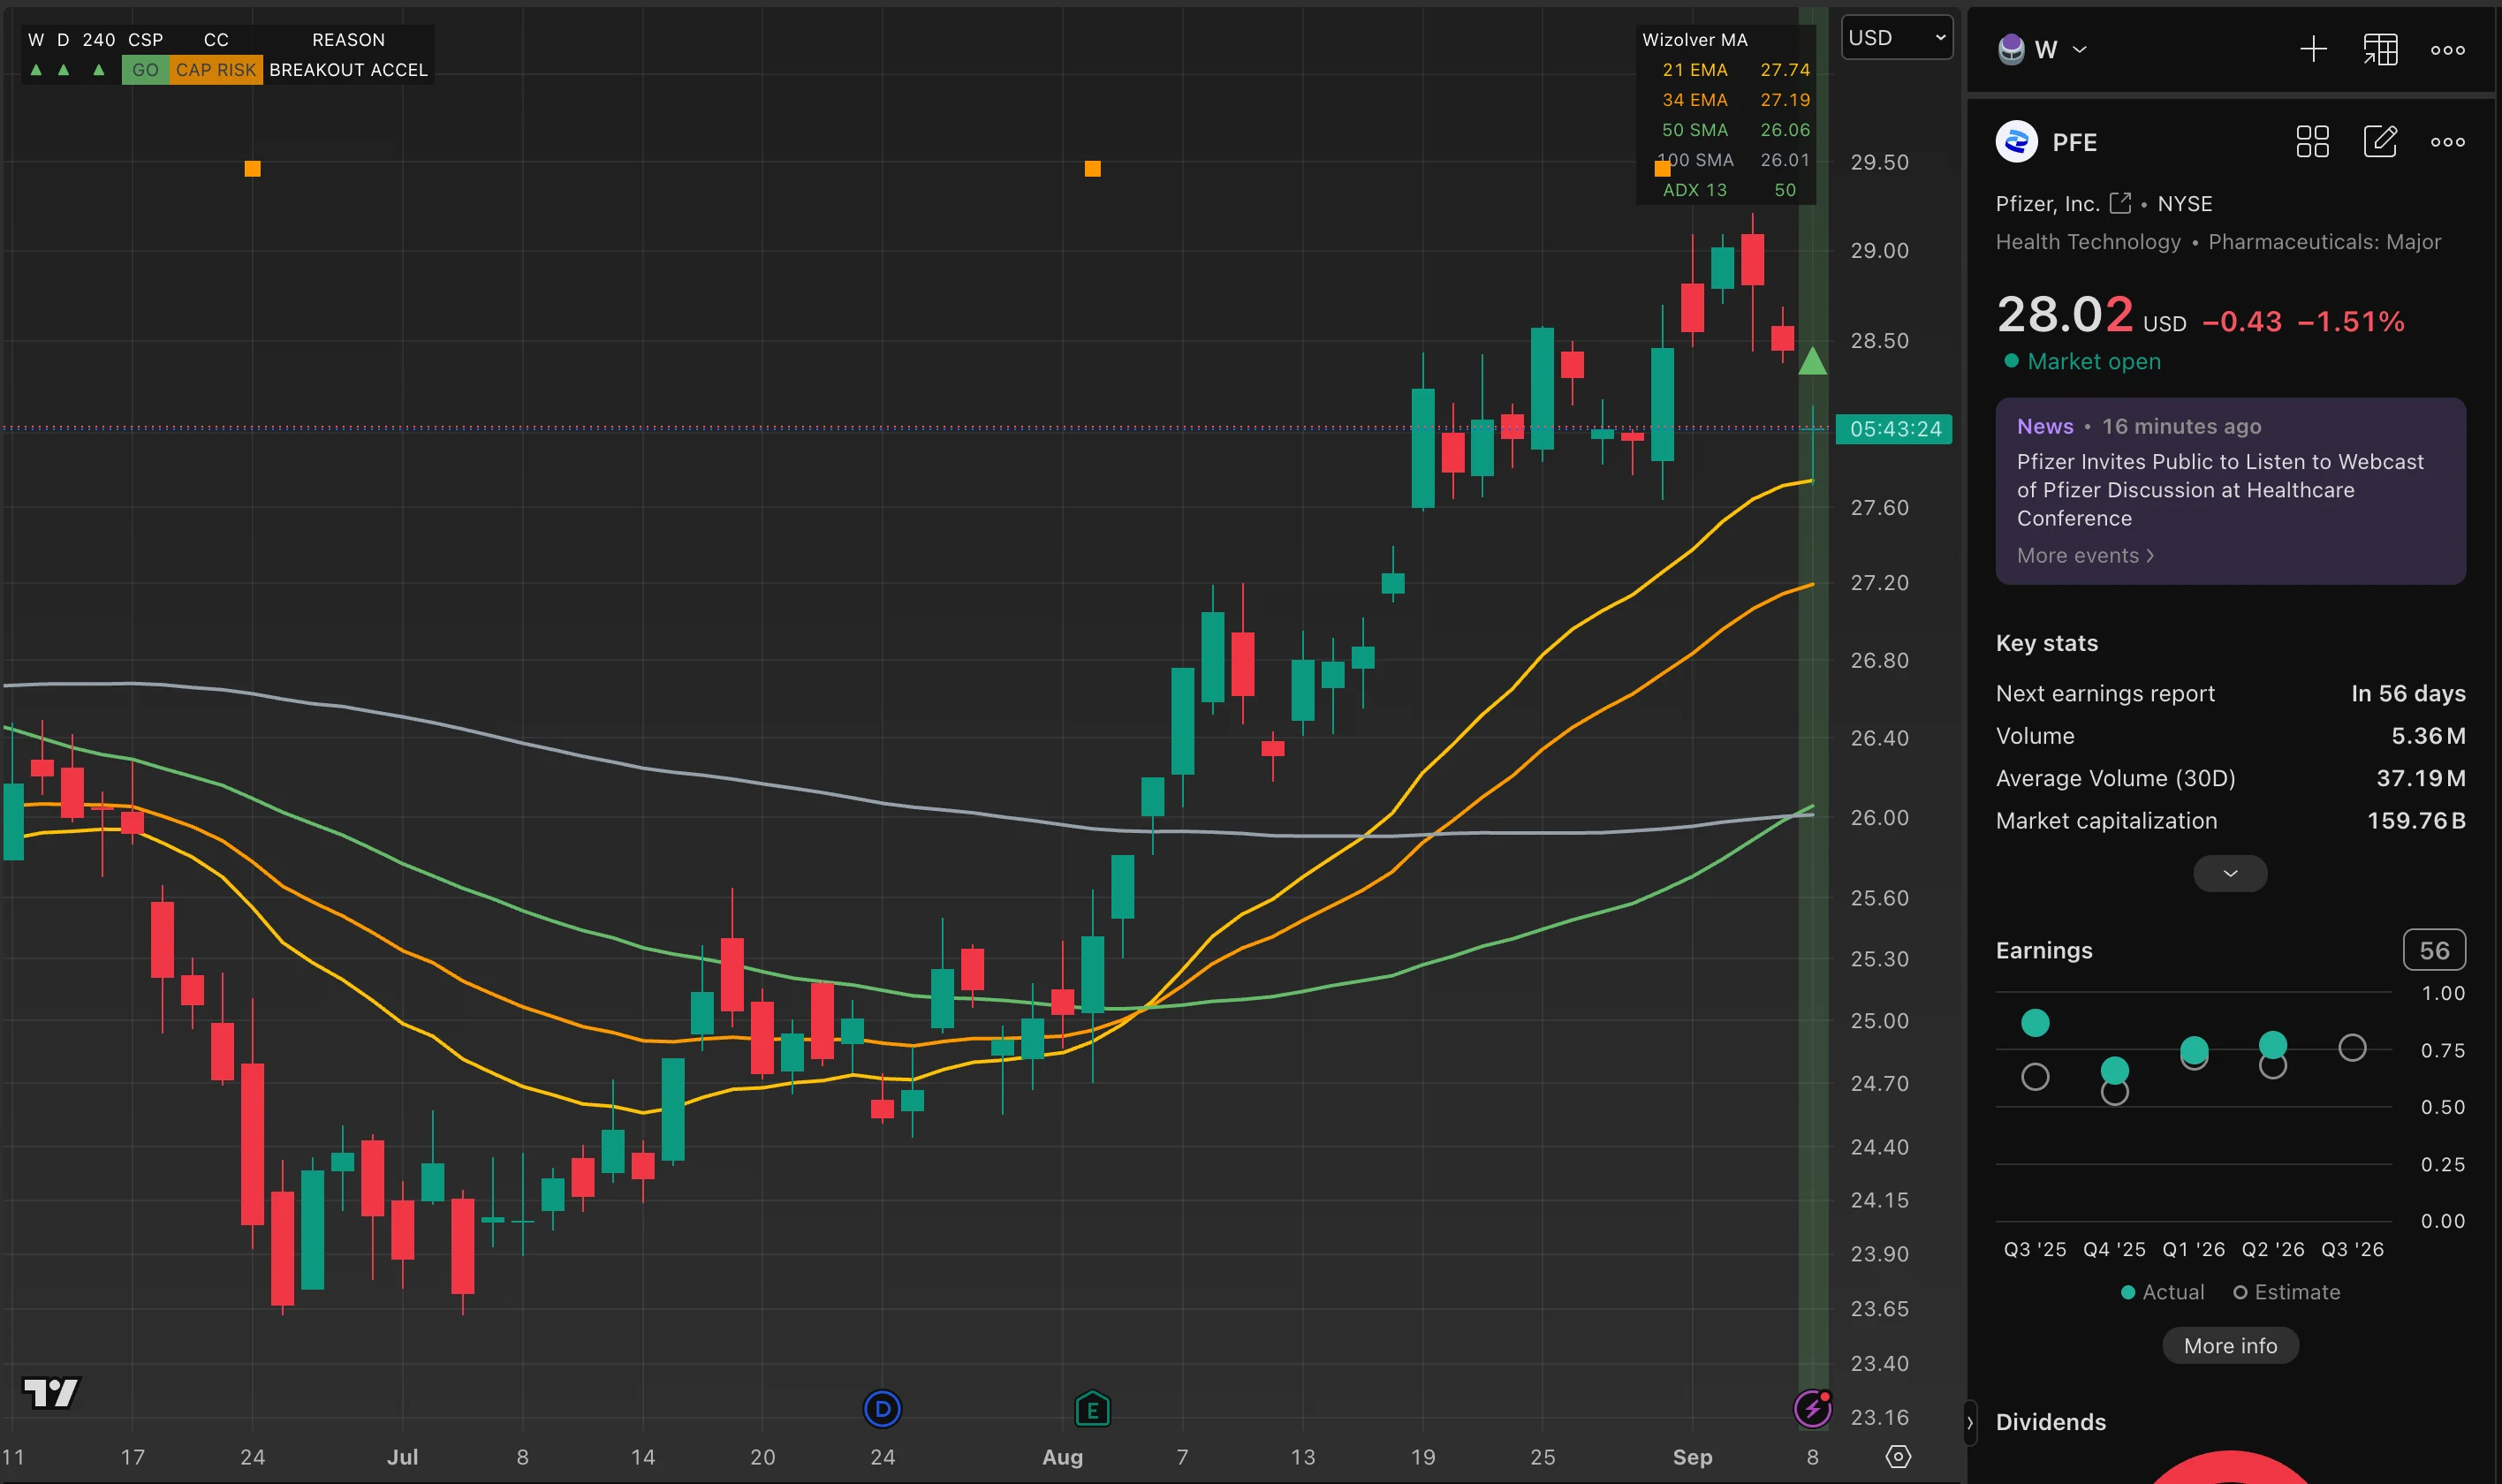
PFE traded around $28.07 when the September 18 $27.50 Cash-Secured Put was evaluated.
The stock has pulled back from a recent high near $29 and is approaching rising short-term moving averages. Unlike several higher-premium watchlist candidates, PFE is not materially extended from its underlying trend structure.
Price remains close to EMA21 near $27.75, while EMA34 sits near $27.20. The $27.50 strike places potential assignment directly inside that support structure.
With approximately 56 days until earnings, there is no immediate earnings-event conflict. The objective is reasonable premium while accepting assignment at a price I am comfortable owning.
Structure
Cash-Secured Put sold at the $27.50 strike, expiring September 18 with 10 days to expiration.
Premium is $0.22 per share, or $220 across 10 contracts. Cash secured is $27,500.
The premium reduces effective assignment basis from $27.50 to $27.28, almost directly on rising EMA34 near $27.20.
The strike is approximately 2% below market price at entry and carries approximately 0.28 delta. The headline cushion is not large, but assignment economics are supported by chart structure.
Assignment Logic
Assignment is an acceptable outcome.
If PFE remains above $27.50 through September 18, the puts expire worthless, the $220 premium is retained, and the $27,500 of secured capital is released.
If PFE closes below $27.50, 1,000 shares enter at the $27.50 strike with an effective assignment basis of $27.28 after premium.
That level sits near EMA34 around $27.20 and below EMA21 around $27.75. SMA50 and SMA100 sit deeper around $26, providing additional structural reference.
Premium is not being used to make an unattractive ownership price acceptable. The ownership price itself is the reason the trade is acceptable.
Premium Context
Premium is fair.
The September 18 $27.50 put provides $0.22 per share with 10 days until expiration, or $220 on $27,500 cash secured.
The premium context is:
- 0.80% return on secured capital
- approximately 29.2% simple annualized APR over 10 days
- implied volatility around 22.5%
- historical volatility near 24%
- no obvious volatility edge
IV is slightly below recent realized volatility, so this premium should not be compared directly with much larger credits in materially higher-volatility names.
The $220 compensates for accepting 1,000 PFE shares at $27.50. The $27.28 effective ownership price and surrounding support structure matter more than maximizing headline APR.
Trade Structure
Management Plan
If PFE remains above $27.50 through September 18, the puts expire worthless, the $220 premium is retained, and secured capital is released.
If assignment occurs, 1,000 shares enter at $27.50 with an effective basis of $27.28 and transition into normal Wheel management.
Covered Calls would be evaluated from the new assignment structure, available premium, and prevailing technical setup.
There is no reason to force an early adjustment simply because PFE trades near strike during the contract life.
The original thesis remains valid as long as structure around current support does not materially deteriorate.
Process Note
Several higher-premium CSP opportunities were available when this trade opened. PFE was not the highest-APR candidate, and that is part of the reason I chose it.
The stock has pulled back toward support rather than sitting far above moving averages after a major rally. At $0.22, the put generates approximately 29% simple annualized APR, below the headline returns in higher-volatility names.
Premium is not the first question. The first question is where I am willing to own shares: approximately $27.28 after premium, near rising EMA34 around $27.20 and with deeper moving-average support around $26.
If PFE stays above $27.50, I collect $220. If assigned, I own 1,000 shares at an effective $27.28. Both outcomes were acceptable before entry. I am prioritizing assignment price and structure underneath it.