Setup
HIMS remains under Wheel management with 400 shares originally assigned at $33 and an effective cost basis of approximately $29.98.
The previous two September 18 $27 recovery CSPs expired worthless, collecting $160 without increasing the 400-share position.
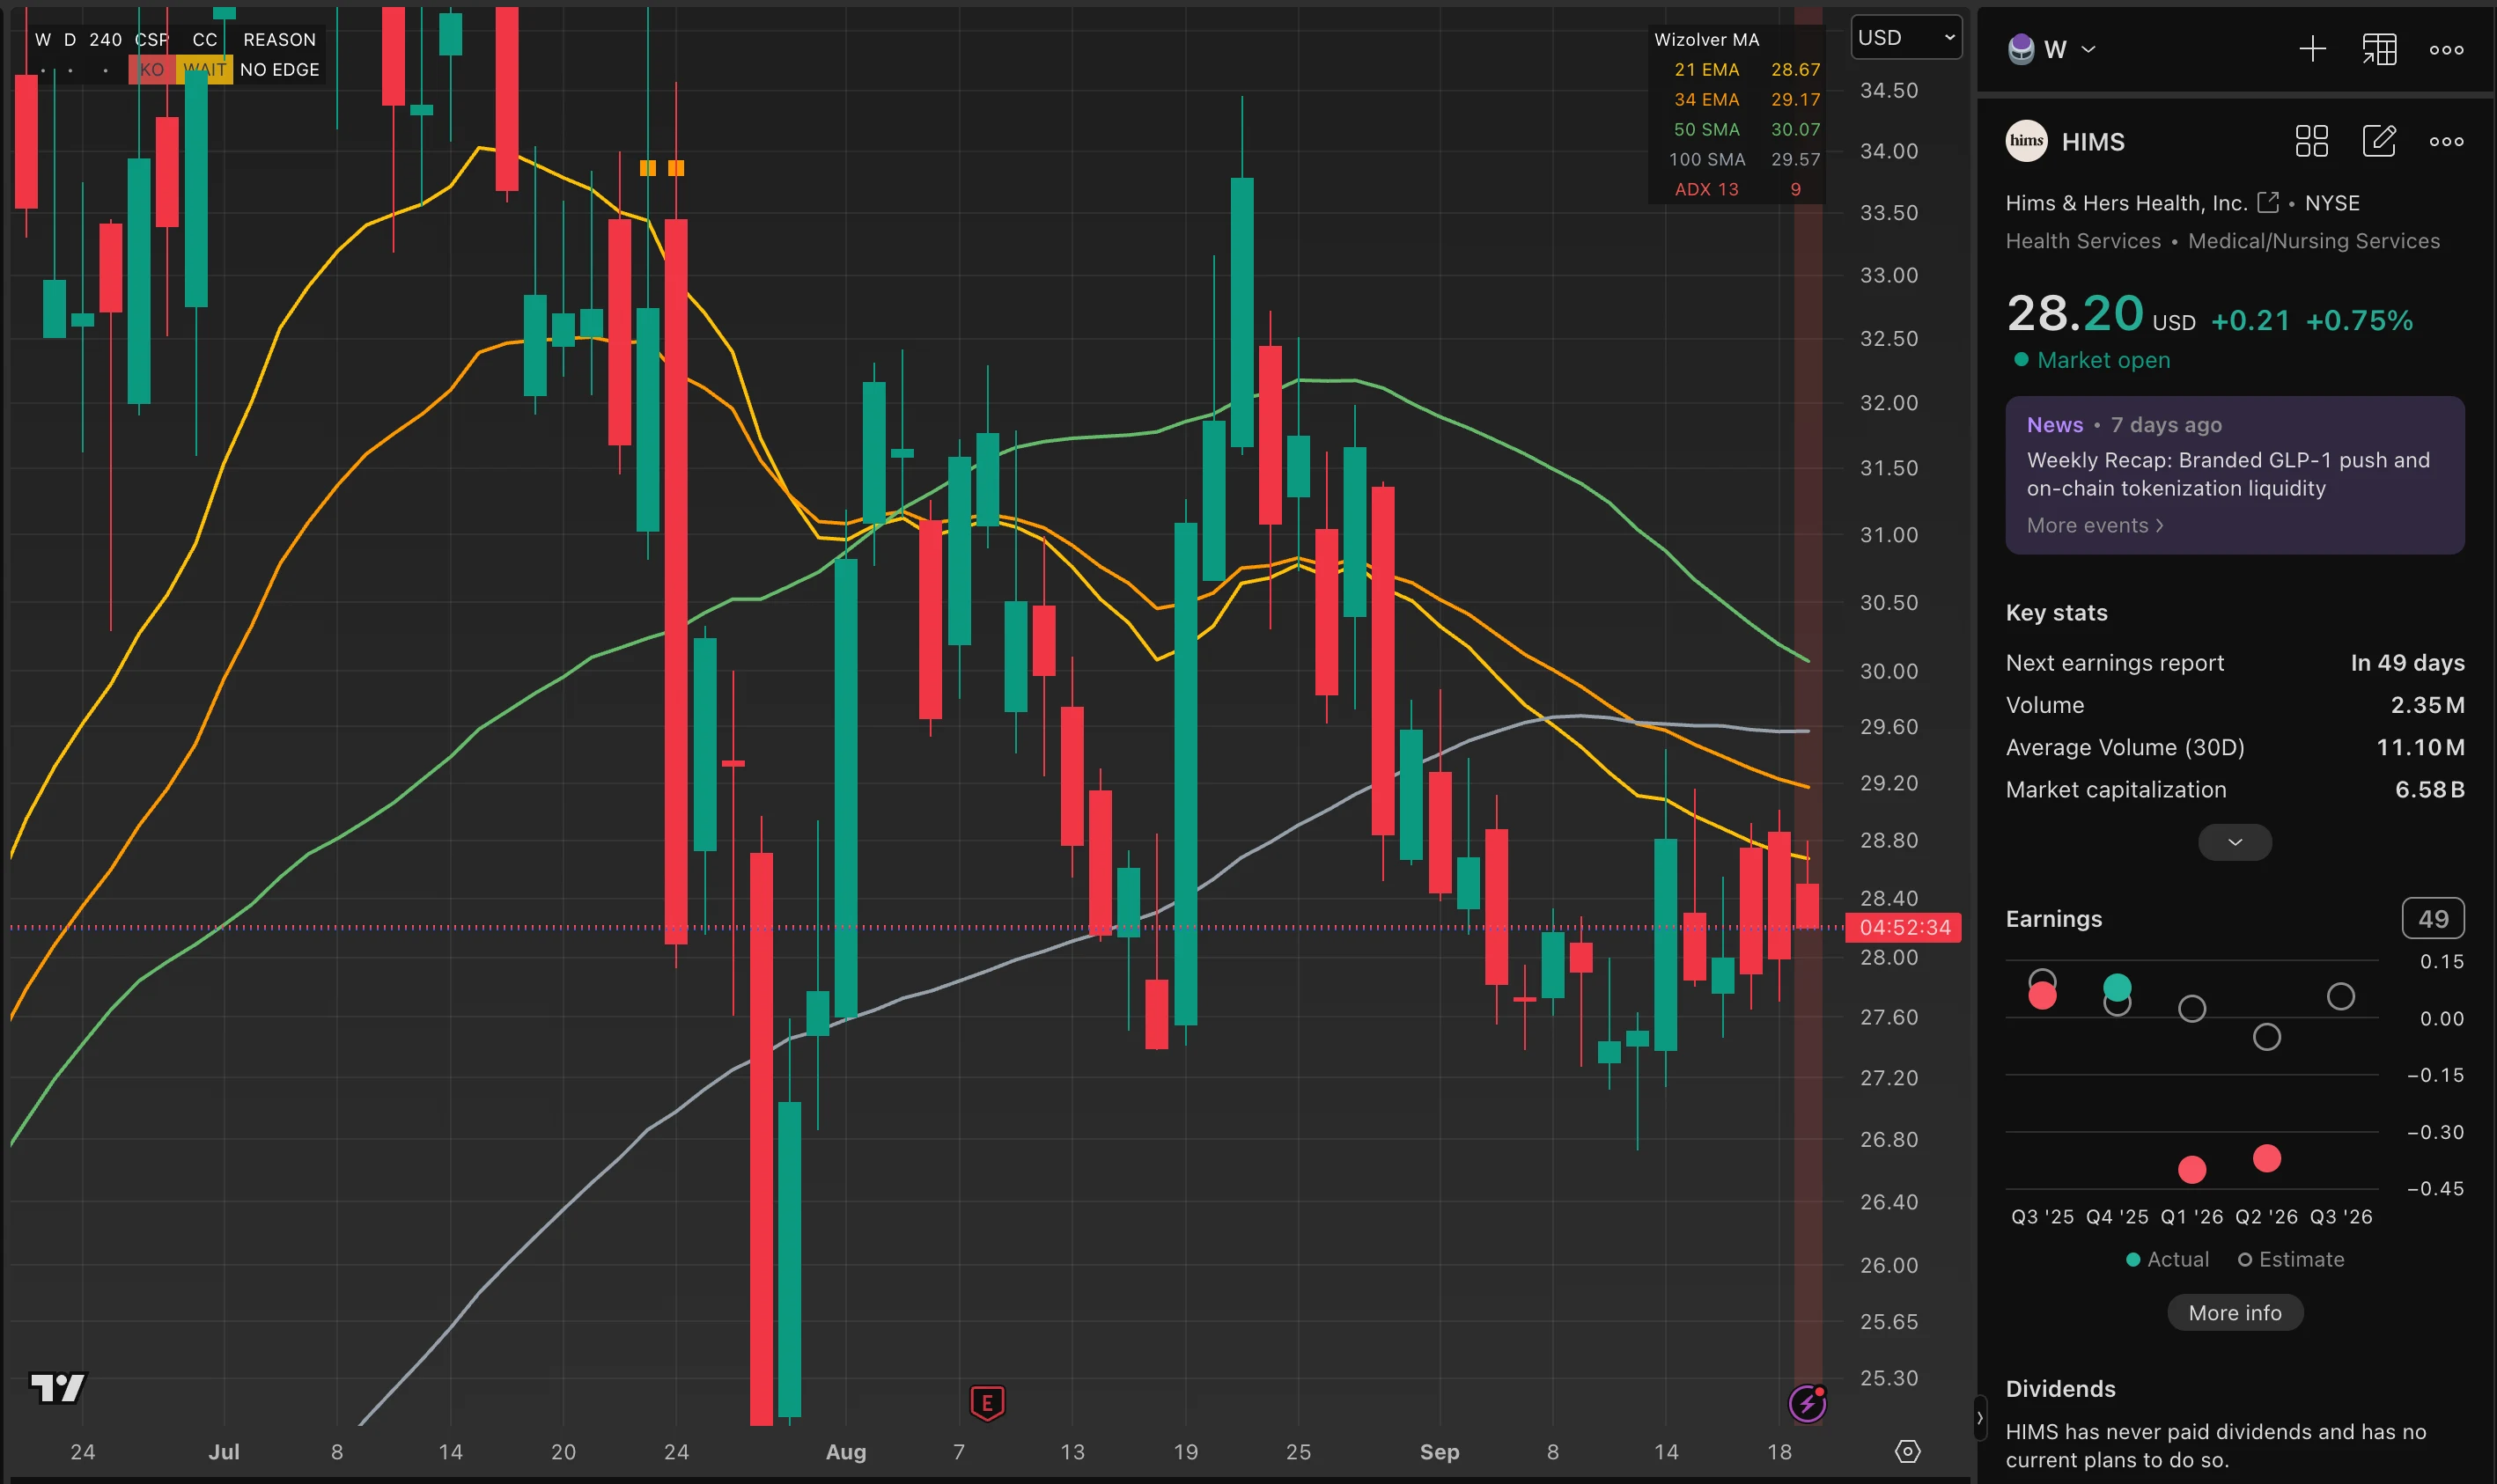
With HIMS near $28.24, the stock remained below the existing basis and the position still needed recovery management.
Three October 2 $28 CSPs were sold at $1.25 to define a more aggressive, but limited, recovery tranche rather than buying 300 shares near market.
Structure
Three Cash-Secured Puts were sold at the $28 strike, expiring October 2, 2026.
The position collected $1.25 per share, or $375 total, against $8,400 in collateral.
Premium reduces the effective assignment basis on new shares to $26.75, below the recent $27-$28 trading area.
If assigned, 300 shares at $26.75 would move the position to 700 shares with an approximate blended basis of $28.60.
Assignment Logic
Assignment is an acceptable outcome.
If HIMS remains above $28 through October 2, the puts expire worthless, the $375 premium is retained, and the $8,400 of secured capital is released.
If assigned, another 300 shares enter at the $28 strike with an effective basis of $26.75.
The complete position would then consist of 700 shares with an approximate blended effective basis of $28.60.
The lower basis improves future Covered Call management, but assignment materially increases exposure from 400 to 700 shares and is not a reduction in underlying risk.
Premium Context
The October 2 $28 put produces $375 on $8,400 in secured capital over 11 days.
That equals a 4.46% return on secured capital, or approximately 148% simple annualized APR.
Premium conditions were fair rather than a standalone volatility edge:
- displayed implied volatility was approximately 65%
- IV Rank was low at around 8-10%
- the strike sat close to the approximately $28.24 market price
- a deeper $27 put offered only around $0.70 per share
- the $1.25 premium still created a $26.75 effective ownership price
The high APR reflects a close-to-market strike in a volatile underlying, not free yield.
The trade needs both outcomes to work: meaningful $375 income if worthless, or a useful blended-basis improvement if assigned.
Trade Structure
Management Plan
If HIMS remains above $28 through October 2, the puts expire worthless, the $375 premium is retained, and secured capital is released.
The existing 400 shares remain under Wheel management while price recovery or another justified recovery trade is evaluated.
If assigned, another 300 shares enter at an effective basis of $26.75 and the blended basis becomes approximately $28.60.
Future Covered Calls would be evaluated against the lower blended basis, not sold aggressively merely because it improved.
The objective is a more manageable ownership structure while preserving an acceptable exit. There is no automatic plan to add beyond this tranche.
Process Note
The prior HIMS recovery puts expired worthless and collected $160 without adding another 200 shares, but did not materially change the $29.98 effective basis.
This recovery uses a $28 strike and three contracts rather than another deeper strike for small premium, making both assignment risk and potential income more meaningful.
If worthless, the trade collects $375. If assigned, 300 shares enter at $26.75 and reduce blended basis to approximately $28.60.
The lower basis does not make HIMS safer; it comes with higher total exposure. Premium and new ownership price both must justify the trade. No prediction. Just process.